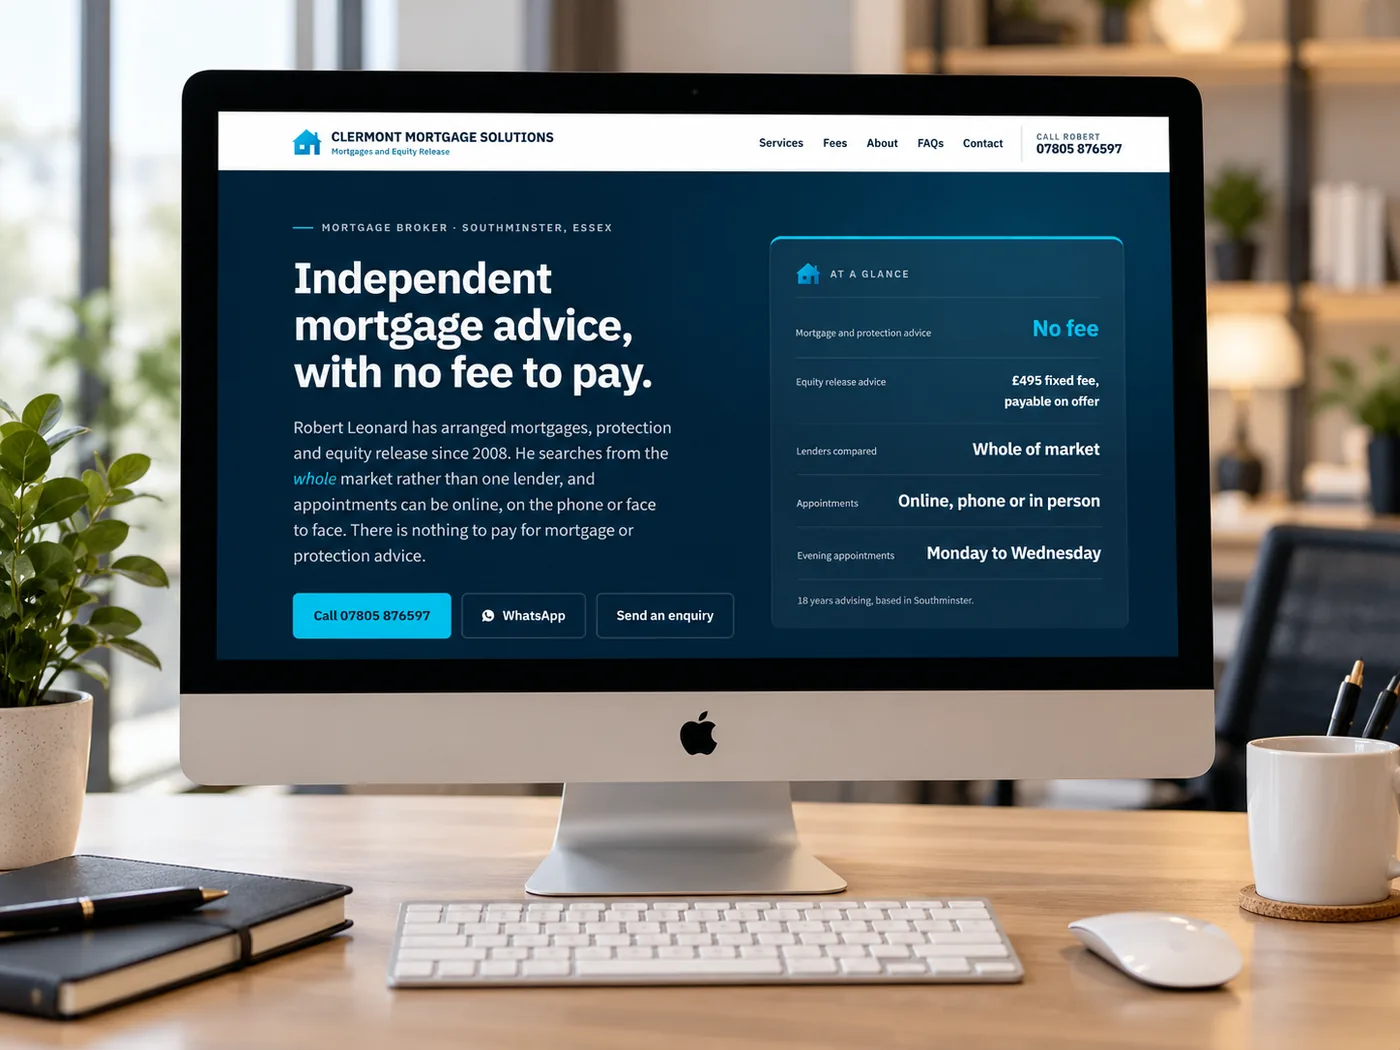
Robert Leonard came to Page Forge for one reason: he needed a website that followed the FCA’s rules. Robert runs Clermont Mortgage Solutions in Southminster, Essex. He is an independent, whole of market mortgage adviser who has been advising since 2008, holds six professional qualifications including CeMAP and CeRER, and covers mortgages, protection and equity release. Most web designers can build a good-looking site. Far fewer understand that, for a regulated firm, the website is a financial promotion, with rules about what it must say and how it says it. The finished site was reviewed and approved by his principal firm’s compliance team. It is live at clermontmortgagesolutions.co.uk.
Why is an FCA-regulated website different?
For a mortgage broker, financial adviser or insurance broker, the website is not just marketing. It is a financial promotion, so it has to be clear, fair and not misleading, and it has to carry specific disclosures. Get it wrong and the problem is not a lost enquiry, it is a compliance issue.
There is a second layer for many advisers. Robert works through a route to market with an authorised principal firm. That means the site has to name the principal firm and its regulatory details correctly, not just Clermont’s, and the wording has to satisfy the principal’s compliance team as well as Robert.
On top of that sits the FCA’s Consumer Duty, which expects firms to communicate in a way customers can actually understand. Pages of dense small print do not meet that. The information has to be there, and it has to be readable.
What does an FCA-compliant website need?
This is what we built into Clermont’s site, and what his principal firm’s compliance team reviewed and approved. If you are an FCA-regulated firm, it is a useful checklist for your own.
- Regulatory status, stated correctly. Who is authorised and regulated, the FCA firm reference number, and, where the adviser works through a principal firm, that firm’s name, FCA number and company number. On Clermont’s site this appears in the About section and again in the footer.
- The mortgage risk warning. “Your home may be repossessed if you do not keep up repayments on your mortgage”, shown clearly rather than hidden.
- Buy to let wording. A clear statement of which buy to let mortgages the FCA does not regulate, because Robert advises on them.
- Equity release warnings. Lifetime mortgages carry specific risks, so the site says plainly that equity release can reduce the value of an estate and may affect means-tested benefits, and points people to a personalised illustration. The equity release service description itself gives the risks alongside the benefits, rather than selling only the upside.
- How the adviser is paid. Clear fee and commission disclosure: no fee for mortgage and protection advice because the lender or insurer pays a commission, and a fixed £495 fee for equity release, payable on offer. The site also promises that clients are told exactly what Robert is paid before they commit.
- Complaints and the Financial Ombudsman Service. How to complain, and a link to the Financial Ombudsman Service if a complaint cannot be resolved.
- Company details. The limited company name and company number, which UK company law requires on a business website.
- A privacy notice. A proper privacy page, because a broker’s enquiry form collects personal and financial information.
- An FAQ that answers “Are you regulated?” People ask it before they call, so the site answers it directly in plain English.
- Fair, balanced copy throughout. No “best rates guaranteed”, no pressure, no claims that cannot be backed up. Every service is described accurately.
How do you make compliance readable?
Disclosures work best when they sit where people need them rather than all piled into one block. The fee explanation lives in a “What it costs” section. The equity release risks sit with the equity release service. The regulatory status appears where people read about the adviser. The formal statements and risk warnings are repeated in the footer, where compliance teams and careful clients expect to find them.
The rest of the site does the normal job of a good broker website: what Robert does, a four-step “how it works”, the areas he covers, evening appointments, and easy ways to get in touch by phone, WhatsApp or an enquiry form. Compliance and conversion do not have to pull against each other. Clear, honest information is what builds trust with a cautious borrower anyway.
How is it set up for Google and AI search?
Behind the page, structured data describes Clermont as a financial service, lists each service and fee, records Robert’s qualifications, marks up the FAQs and names the areas he covers. That gives Google and AI assistants accurate, machine-readable facts to work from, which matters in a search space dominated by national comparison sites. Rankings are never guaranteed, but a regulated firm that states its facts clearly gives itself the best foundation.
If you run an FCA-regulated firm, see how we build FCA-compliant websites, and our pages for mortgage advisers, financial advisers and insurance brokers. We work UK-wide, including web design in Essex.
Frequently asked questions
Can you guarantee my website will be FCA compliant?
No web developer honestly can, and you should be wary of any who says otherwise. The FCA does not approve or certify websites, and responsibility for your financial promotions stays with your firm, or with your principal firm if you are an appointed representative. What we do is build every required disclosure in, write clear and balanced copy, and make the site simple for your compliance team to review. Clermont’s site, for example, went through its principal firm’s compliance review and was approved.
I am an appointed representative. Can you work with my network’s compliance team?
Yes. We word your regulatory status and your relationship with your principal firm correctly, and we work to the wording and changes your network’s compliance team asks for. When they request edits, we turn them around quickly. That is exactly how Clermont’s site was taken through its principal firm’s compliance approval.
Which FCA-regulated businesses do you build for?
Mortgage brokers and advisers, independent financial advisers, protection specialists, equity release advisers and insurance brokers. The regulatory detail differs between them, and we build each site around the disclosures that firm actually needs.
Can you update risk warnings or disclosures when the rules change?
Yes. Updates are part of our service, so when your compliance team needs wording changed, a fee updated or a new disclosure added, you tell us and we make the change. You never have to log in and edit it yourself.
How much does an FCA-compliant website cost?
A one-page site is £99 to set up and £29 a month, or £299 for the year, with the domain, hosting, SSL and writing included. Larger firms that need more pages are quoted individually. Our prices are on the pricing page.
The rules built in, written so people can actually read them.